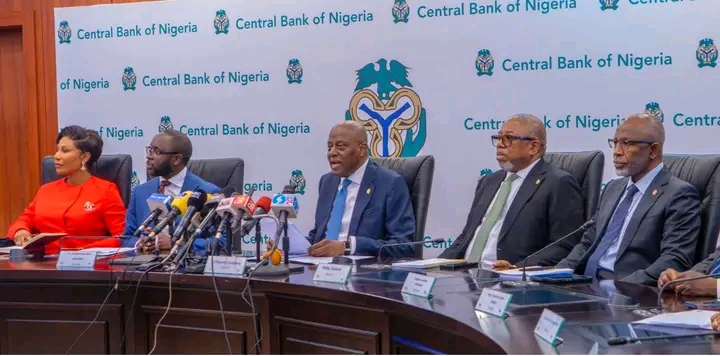
The Central Bank of Nigeria (CBN) has reduced its Monetary Policy Rate (MPR) from 26.5 per cent to 23 per cent, signalling a shift towards a less restrictive monetary policy stance as inflationary pressures moderate.
CBN Governor, Olayemi Cardoso, announced the decision on Tuesday after the 306th meeting of the Monetary Policy Committee (MPC), held on September 21, 2026.
Cardoso said the committee was satisfied with the progress recorded in disinflation and noted the stability of the banking sector following the successful recapitalisation of banks.
The latest decision represents a 350-basis-point reduction in the benchmark interest rate from the 26.5 per cent maintained at the MPC’s previous meeting. The CBN had retained the rate at 26.5 per cent amid concerns about inflation and external shocks.
The reduction marks a significant easing of monetary conditions after a period of tight policy aimed at containing inflation and stabilising the macroeconomic environment.
_Implications for businesses_
The reduction could gradually lower the cost of borrowing for businesses, particularly if commercial banks transmit the lower policy rate to lending rates.
For manufacturers, traders and other businesses that depend heavily on bank credit, cheaper financing could reduce interest expenses and make it easier to fund working capital, purchase equipment and expand operations.
Small and medium-sized enterprises (SMEs), which often face high borrowing costs, could also benefit if banks respond by reducing lending rates. Increased access to credit could support investment, production and employment.
However, the impact is unlikely to be immediate or uniform. The MPR is a benchmark for monetary conditions, while actual lending rates are influenced by banks’ funding costs, credit risks, liquidity conditions and operating expenses.
The CBN itself has identified the credit, interest-rate and other channels as mechanisms through which monetary policy affects economic activity.
_Impact on the economy_
The rate cut could provide additional support for economic activity by encouraging borrowing, investment and consumption. If businesses obtain cheaper credit and use it to expand production, the policy could contribute to higher output and job creation.
It could also improve conditions for sectors that are particularly sensitive to financing costs, including manufacturing, construction, real estate, agriculture and consumer businesses.
The move, however, presents a policy balancing act. Faster credit expansion and increased liquidity could generate additional demand and potentially put pressure on prices if domestic production does not increase sufficiently.
There could also be implications for savings and investment returns. Lower interest rates can reduce returns on some fixed-income and deposit instruments, while potentially making riskier productive investments relatively more attractive.
For government finances, a sustained decline in market interest rates could eventually reduce the cost of new domestic borrowing, although the immediate effect would depend on prevailing yields and the structure of government debt.
The decision suggests that the MPC believes inflation has made sufficient progress for monetary policy to shift from an exceptionally tight stance towards supporting economic activity.
The CBN has been pursuing an inflation-targeting framework in which interest rates and other monetary tools are adjusted in response to inflation and broader economic conditions.
The key issue for businesses and investors will now be whether the reduction is transmitted through the financial system into significantly lower lending rates and whether the improvement in inflation is sustained.
If both conditions hold, the policy could create greater room for private-sector investment and economic expansion. However, if inflationary pressures return, however, the CBN could face pressure to reconsider the pace of monetary easing.